Published October 7, 2026 · Roofing Giant Editorial Team
Updated from primary Texas Department of Insurance materials filed through October 1, 2026.
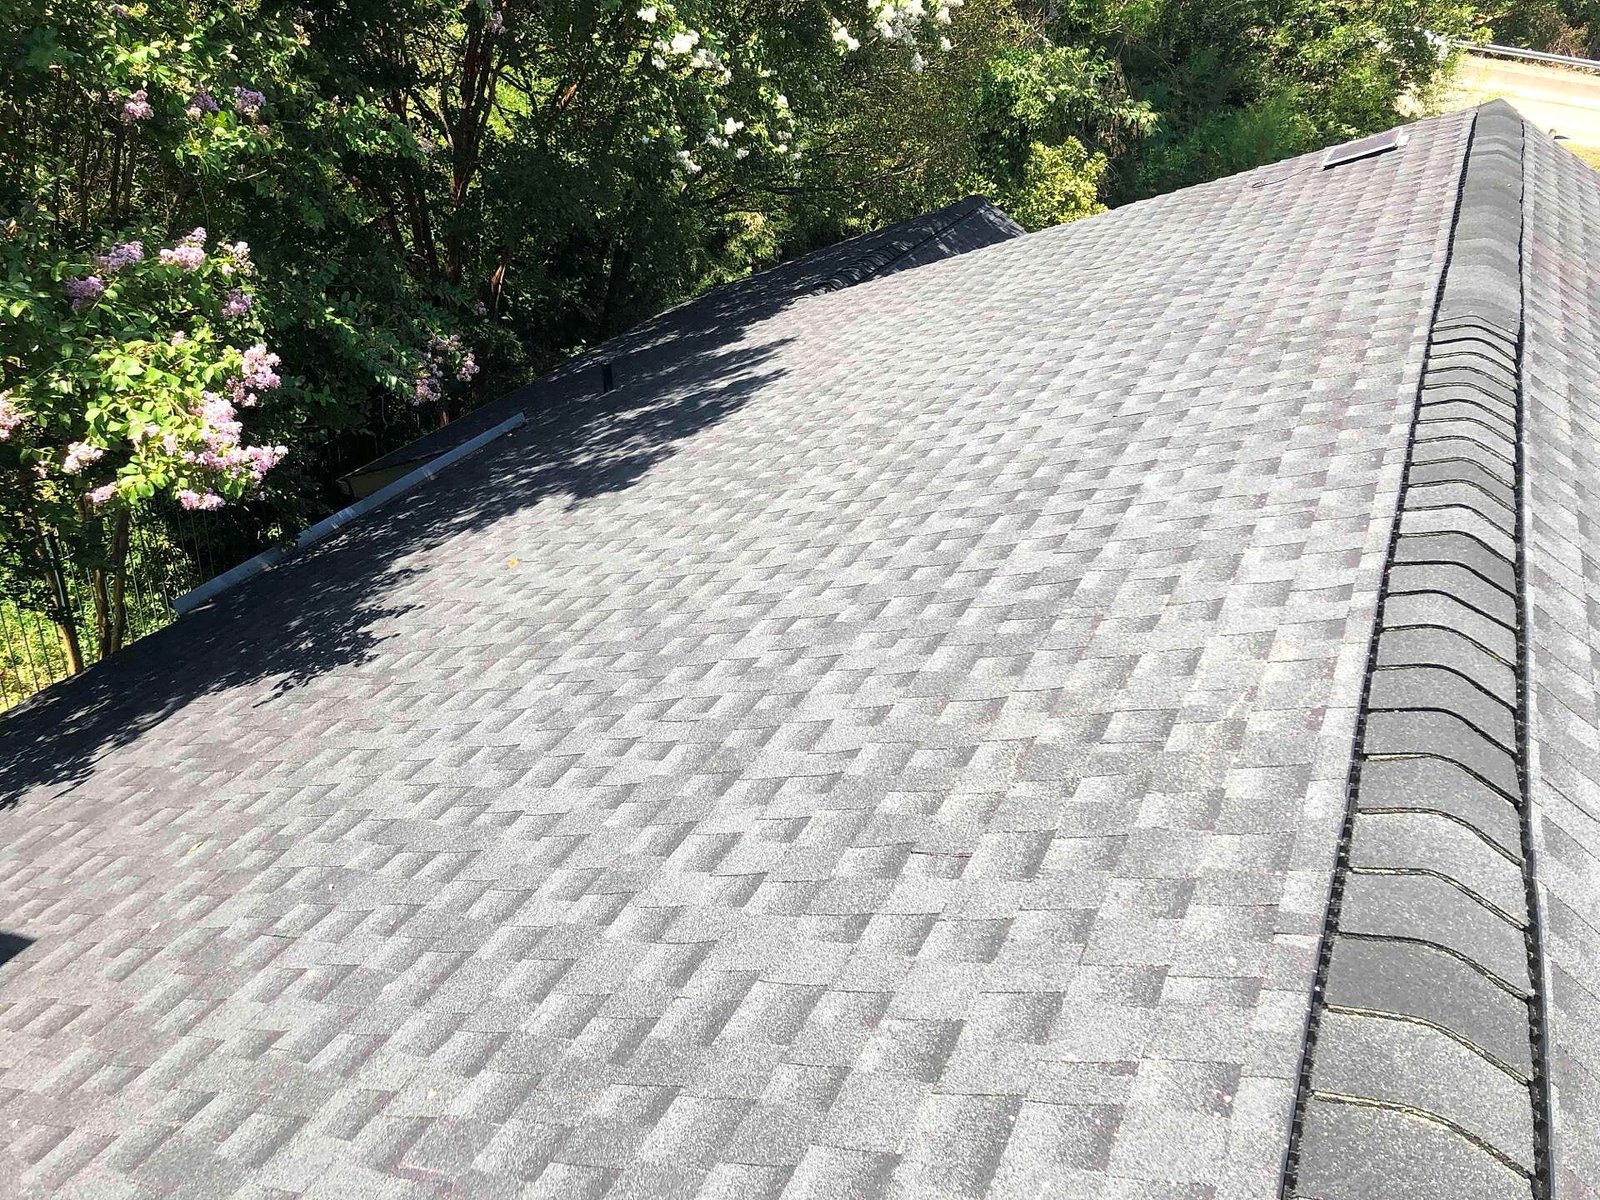
The Texas Department of Insurance (TDI) filed a proposed clarification on September 29, 2026, aimed at making one distinction unmistakable: the age of a house or roof is not the same thing as its physical condition. TDI says the existing rule prohibits insurers from refusing to write or renew residential property insurance based only on the age of the property or its components, including roofing. The proposed text preserves an insurer’s ability to evaluate actual physical condition.
The practical distinction
Roof age is a date. Roof condition is evidence.
Age alone
The proposed clarification says an insurer may not decline residential property insurance merely because the property—or a component such as roofing—is a certain age.
Physical condition
The rule does not prevent an insurer from considering documented physical condition, including deterioration, maintenance issues or other observable risk factors.
Roofing Giant original explainer graphic, based on proposed 28 TAC §21.1006. It is a plain-language summary, not a coverage determination.
What changed—and what has not
TDI’s six-page proposal says the amendments are clarifying, not a new expansion of the rule. The proposal reorganizes §21.1006, expressly names individual property components and materials, and lists roofing among the examples. It also moves the physical-condition exception into its own subsection.
As of this publication date, the amendment is still proposed. TDI’s rule calendar shows the proposal was filed September 29 and is scheduled for publication in the Texas Register on October 9. A hybrid public hearing under Docket No. 2874 is scheduled for November 3 at 2 p.m. Central, and written comments are due to TDI by November 9 at 5 p.m. Central. No adoption or effective date is listed for this proposal yet.
That status matters. TDI describes the filing as a clarification of its long-standing interpretation, but homeowners should not describe the amendment itself as already adopted.
Why roof documentation still matters in Dallas–Fort Worth
The proposal does not make roof condition irrelevant. In a hail- and wind-exposed market such as DFW, a homeowner may need to show what is known about the roof rather than relying on age alone. Useful records can include:
- the installation or replacement date and paid invoice;
- manufacturer, product line and material type;
- permit and final-inspection records, when applicable;
- dated photographs of slopes, ridges, flashing, penetrations, drainage and attic ventilation;
- records of repairs and routine maintenance;
- a recent professional condition report that separates active defects from normal aging; and
- any manufacturer warranty or impact-resistance documentation.
A condition inspection should report observable facts. It should not promise insurance eligibility, predict a claim outcome or substitute for an insurer’s underwriting inspection.
If an insurer declines or does not renew a policy
Ask the insurer or agent for the written reason and preserve the notice. Texas law now requires insurers to report and explain reasons for residential-property declinations, cancellations and nonrenewals, and TDI publishes aggregated reasons by ZIP code and policy type. TDI’s public reason categories include property condition, claims history, wind/hail exposure and other underwriting factors.
If the notice appears to rely only on the roof’s age, ask the insurer to identify the physical condition or other underwriting basis it used. For questions about Texas insurance rights, contact TDI directly at tdi.texas.gov or 800-252-3439. Roofing Giant does not interpret policy coverage or determine whether an insurer must issue or renew a policy.
What this rule does not guarantee
- It does not guarantee that a particular insurer will write or renew a policy.
- It does not prevent underwriting based on the roof’s actual physical condition or other lawful factors.
- It does not determine whether storm damage is covered or how a claim will be settled.
- It does not mean every older roof needs replacement—or that an older roof is problem-free.
Methodology and limitations
The Roofing Giant Editorial Team reviewed the TDI September 29 news release, the proposed rule text for 28 TAC §21.1006, TDI’s 2026 rule-status table and TDI’s residential-policy action/reason database on October 7, 2026. We compared the agency’s plain-language announcement with the formal proposal to distinguish current rule interpretation from pending rulemaking. This article does not analyze carrier-specific underwriting manuals, individual policy language or a homeowner’s complete property condition. Rule status may change after publication; we will correct or update this report when TDI posts an adoption, withdrawal or material revision.
Primary sources
- TDI: Texas homeowners protected from being denied insurance based on roof age (September 29, 2026)
- TDI proposed amendment to 28 TAC §21.1006 (filed September 29, 2026)
- TDI proposed and adopted rules for 2026 (status table)
- TDI residential policy actions and reasons by ZIP code
- TDI Docket No. 2874 hearing notice
More DFW Roofing Field Reports
Explore Roofing Giant’s source-first local research on project data, permits, storm context, cost and contractor verification at the DFW Roofing Field Reports hub.