Allen, Texas · Farmers / Fire Insurance Exchange · 2017 project records
A documented Allen supplement added $5,949.20 to the starting carrier RCV. The revised Fire Insurance Exchange report shows additional flashing, gutter-access and labor items, together with the overhead and profit reflected in its final total.
View the original reports — before and after
Starting estimate → documented outcome
$5,949.20 higher · +55.5%
| Component | Starting | Later report |
|---|---|---|
| Line-item subtotal | $10,469.92 | $13,605.03 |
| Material sales tax | $254.86 | $289.93 |
| Separately listed contractor overhead | — | $1,389.51 |
| Separately listed contractor profit | — | $1,389.51 |
| Total RCV | $10,724.78 | $16,673.98 |
An em dash means the component was not separately listed in that source summary.
Same-claim building-coverage RCV, including roof, gutter and other exterior construction items. Not a roof-only or cash-payment comparison.
RCV means replacement cost value, not net insurance payment. This selected historical outcome does not predict another claim’s result.
Photographs from this project file
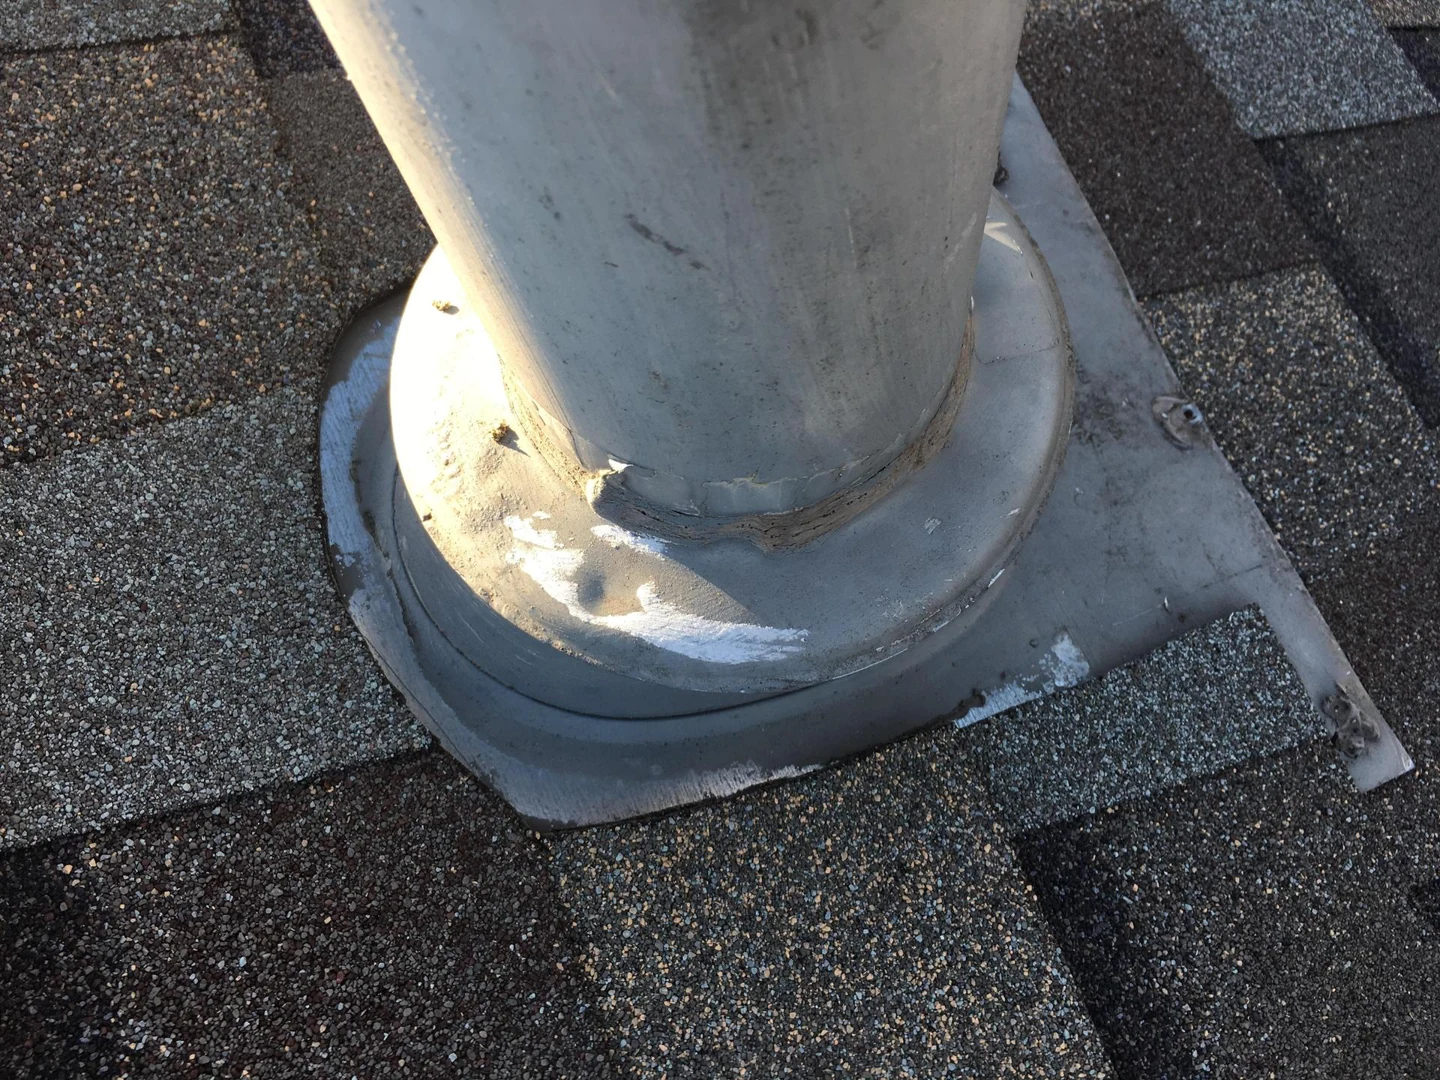
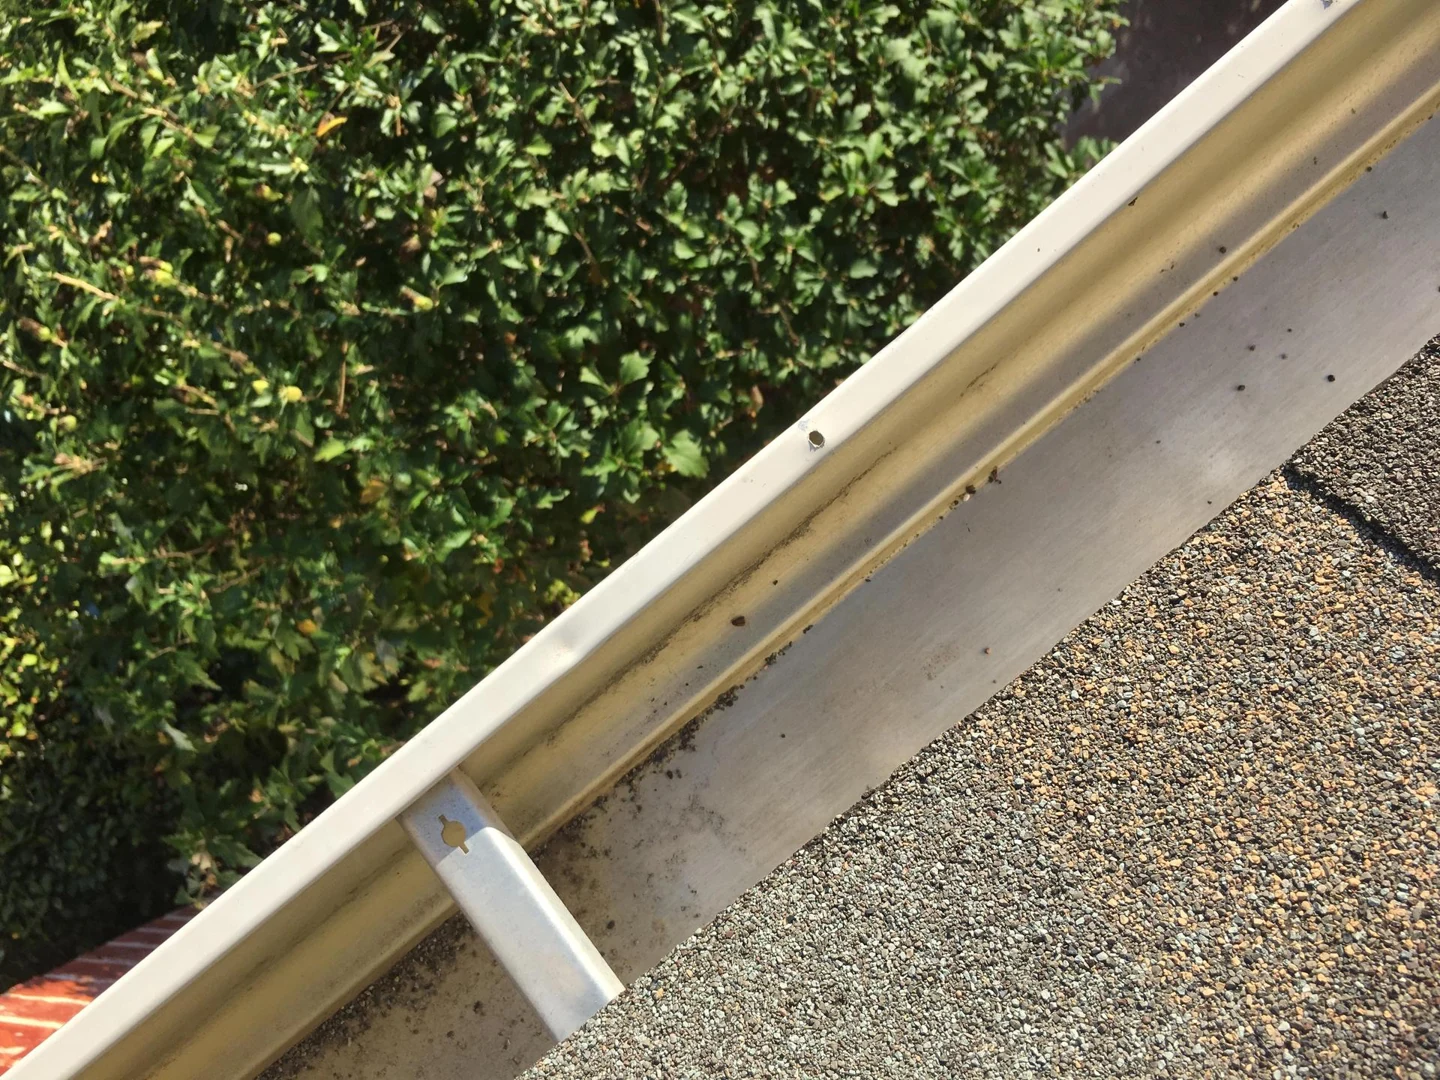
These photographs document recorded conditions. They do not, by themselves, establish damage causation, coverage or completed repairs.
The starting estimate
The October 17, 2017 carrier estimate for this Allen property showed $10,724.78 RCV. The estimate identifies Fire Insurance Exchange; the accompanying settlement correspondence and claims contact use Farmers branding. The comparison follows the same property, claim and building-coverage summary through both documents.
The supplement addressed how the repairs would be performed
Roofing Giant’s project notes record preparation of the supplement on October 25 and submission to Farmers on October 26. A November note describes follow-up over detaching and resetting gutters. The later carrier estimate documents that work and explains why it was included.
In the November 20 revision, 295 linear feet of gutter/downspout detach-and-reset work appears on page 6. The carrier’s note says this allows drip edge to be installed underneath. The revised report also lists 255.27 linear feet of drip edge, 53 linear feet of step flashing, chimney flashing, counterflashing and four roofer labor hours for hand carrying material where the roof could not be loaded.
Other visible changes include glazing bead increasing from 27 to 47 linear feet and two window screens, with the carrier noting that the contractor provided a supporting photograph. These descriptions come from the actual historical estimate; they are not blanket statements about what another insurer or current building code will require.
The revised carrier result
The November 20, 2017 report shows a line-item subtotal of $13,605.03, material sales tax of $289.93, and separately listed overhead and profit of $1,389.51 each. Its replacement-cost total is $16,673.98.
That is $5,949.20 above the $10,724.78 starting RCV — a 55.5% increase. A December 5 project note records the same $5,949.20 as approved supplement money, independently matching the two report totals.
A line-item result, not a percentage promise
The strongest evidence in this case is not only the difference between totals. It is the connection between specific repair-sequencing requirements, the submitted supplement and the items documented in the revised carrier estimate.
The public comparison includes building, roof, gutter and other exterior scope, together with the taxes and overhead/profit shown in the reports. It is not presented as a roof-only increase, a net insurance payment or a guarantee of a similar result. Roofing Giant’s role was to document construction requirements; the carrier made its own approval and payment determinations.
Original reports — before and after
Original source documents — redacted for privacy. Estimate entries and amounts unchanged. Every page in these retained files is included. Carrier names and branding, descriptions, quantities, prices where provided, taxes, depreciation, overhead/profit and totals are preserved. Homeowner names, addresses, personal contact details, claim/policy numbers, signatures and identifying metadata have been removed. Unredacted originals remain private.
Allen — Farmers / Fire Insurance Exchange
Starting carrier estimate
Open PDF · 10 pagesRevised carrier estimate
Open PDF · 8 pagesThe 10-page starting packet includes its two-page settlement notice and eight-page estimate, so file-page numbers differ from printed estimate-page numbers. The later eight-page report is preserved in full. Both comparisons use building-coverage RCV.
Source records and calculation
- Starting carrier packet dated October 17, 2017: 2 settlement-letter pages followed by an 8-page estimate. Itemized scope is on file pages 6–7; the RCV summary is on file page 9, printed estimate page 7. All 10 retained pages are included.
- Revised Fire Insurance Exchange estimate dated November 20, 2017: itemized scope and explanatory notes, pages 4–6; RCV summary, page 7; taxes and overhead/profit recap, page 8. All 8 retained pages are included.
- Private CRM notes dated October 26 and December 5, 2017 document supplement submission and the matching $5,949.20 approved increase.
Increase = ($16,673.98 − $10,724.78) ÷ $10,724.78 × 100 = 55.5%, rounded to one decimal. The baseline is the verified starting carrier estimate retained in the project file, not an assertion that the insurer never created an earlier version. Both amounts refer to the same claim and coverage basis.
Does the repair scope match the property?
Request a roof inspection and a documented construction-scope review.
Schedule a Free Roof InspectionImportant: These are selected historical outcomes, not typical-results claims or guarantees of approval, payment or percentage increase. Replacement cost value (RCV) is not net payment, a final construction invoice or proof that every estimated item was performed. Deductibles, depreciation, prior payments, coverage and policy terms affect what is payable. Roofing Giant is a roofing contractor that manages qualified roofing crews/subcontractors to Roofing Giant standards. Roofing Giant is not a public adjuster and does not determine policy coverage or claim settlement. Information only; not insurance, public-adjusting, financial or legal advice.