North Richland Hills, Texas · documented insurance-scope case study
A wind-and-hail project where the starting carrier replacement-cost estimate was $1,555.69 and the subsequent appraisal/umpire estimate totaled $19,262.58.
View the original itemized reports — before and after
Starting estimate → documented outcome
$17,706.89 higher · +1,138.2%
| Scope | Starting | Later record |
|---|---|---|
| Dwelling | $1,555.69 | $19,262.58 |
Dwelling estimate, including roofing and interior work. Not a roof-only total.
RCV means replacement cost value. These amounts are not the homeowner’s net insurance payment and do not promise a similar result on another claim.
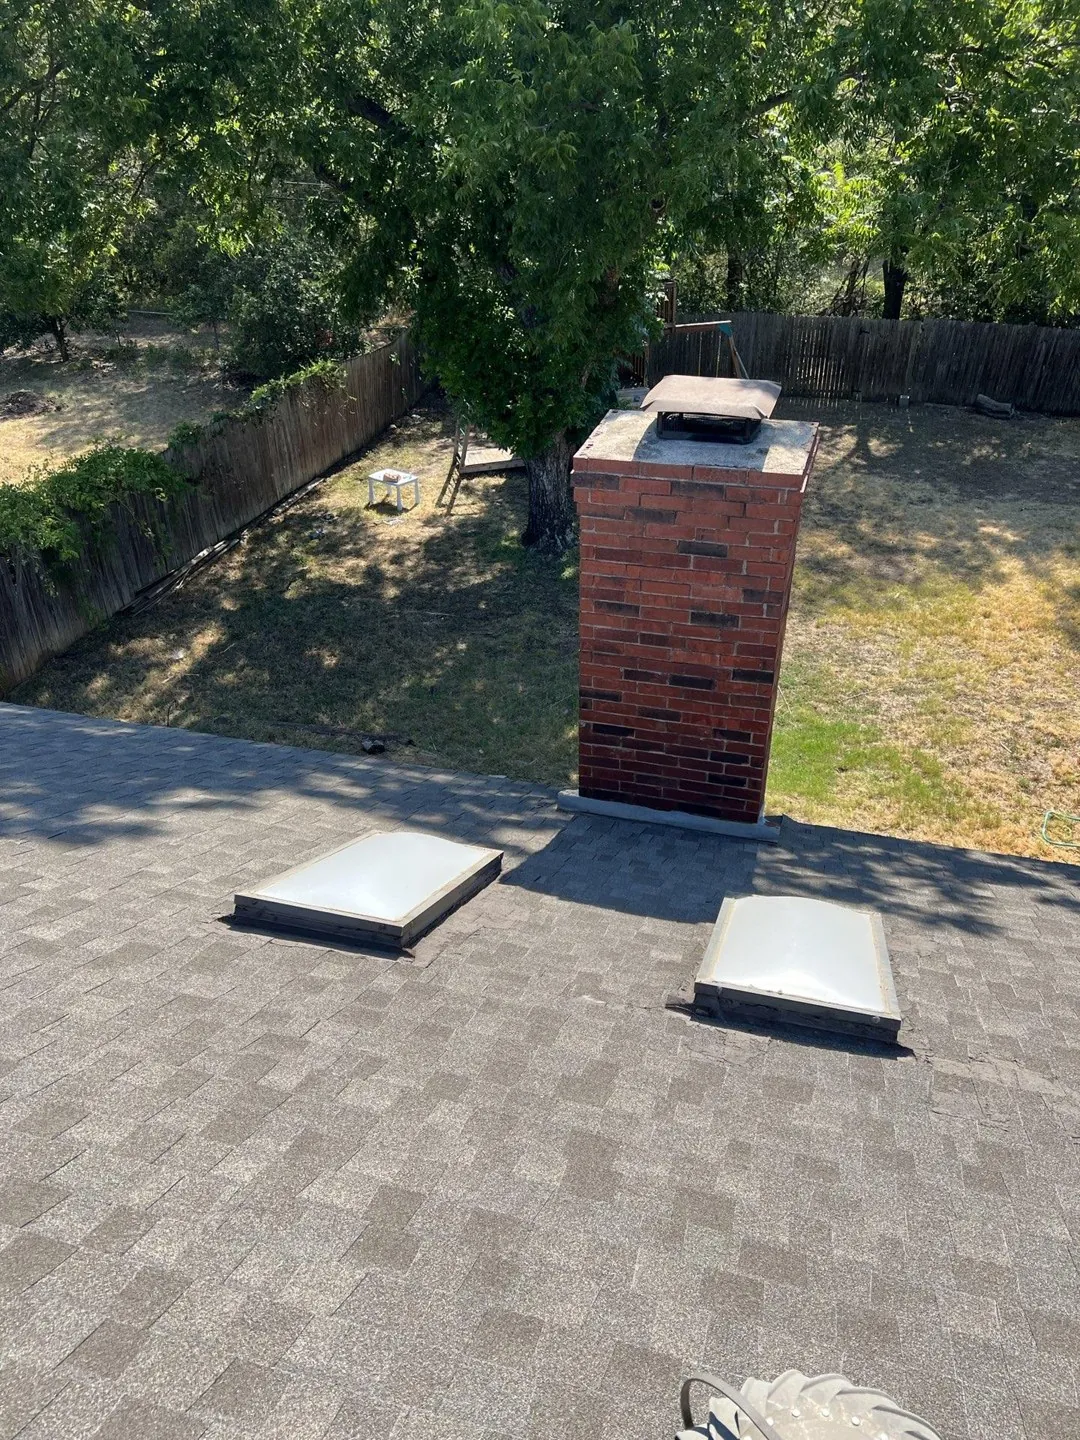
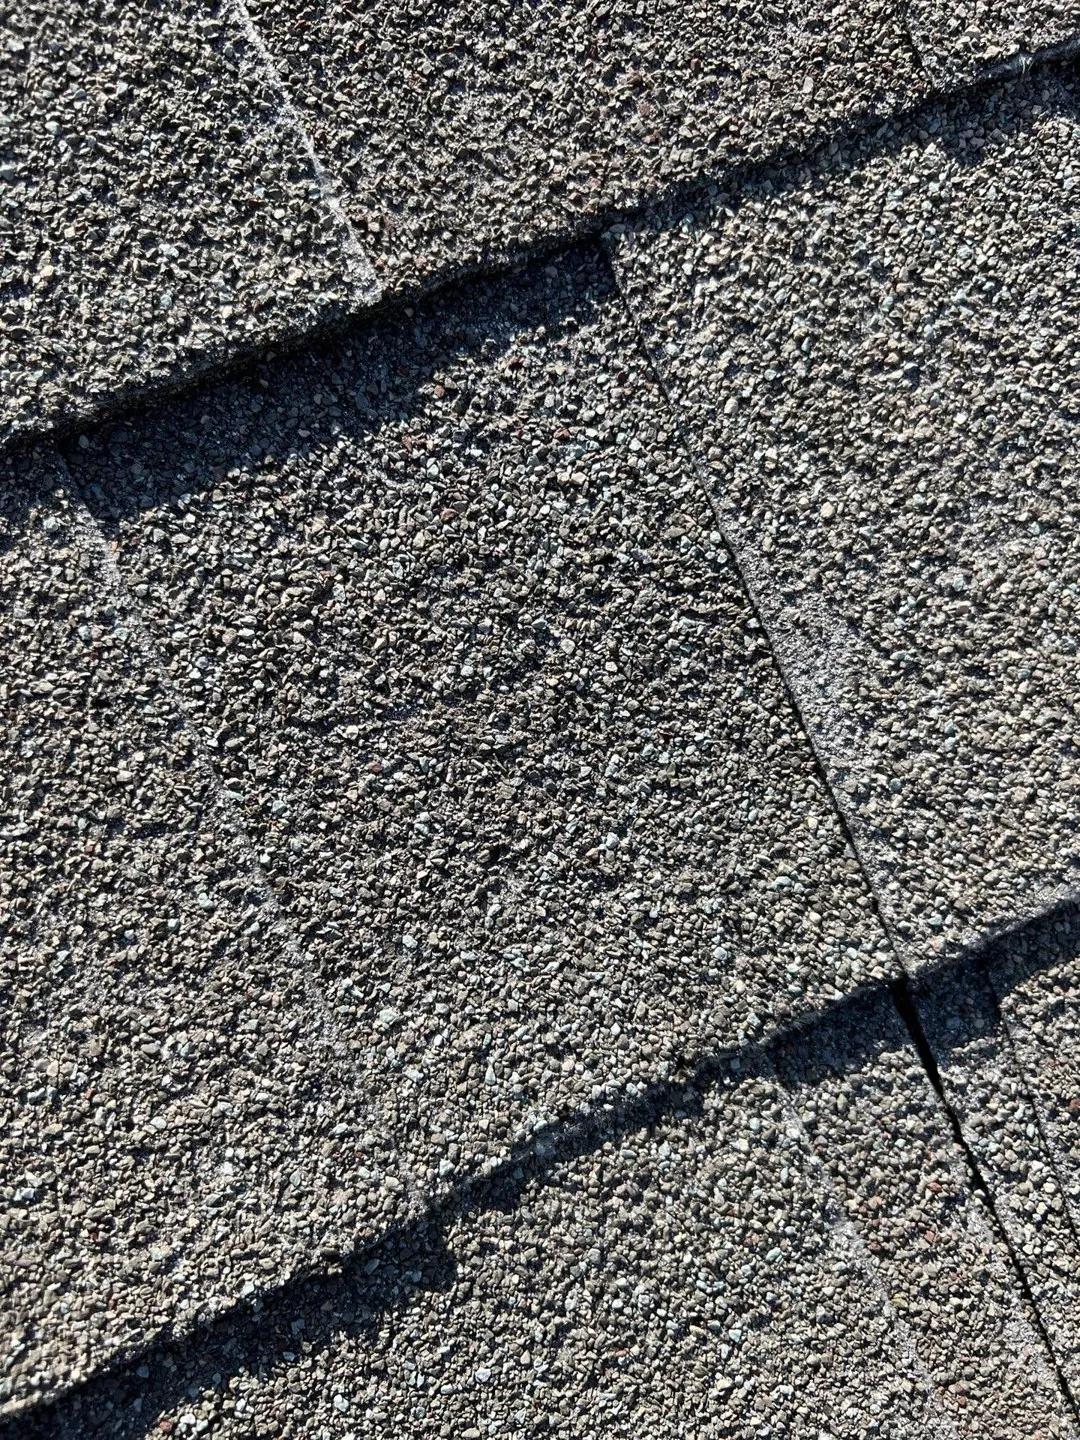
Photographs from this project file
The starting estimate
The project file contains the carrier’s starting estimate showing a replacement cost value of $1,555.69. The later appraisal record contains a materially broader construction scope than this starting estimate reflected.
What changed in the documented scope
The later appraisal/umpire estimate included roofing work plus interior-related work, general demolition, drywall, insulation, electrical items, painting, cleaning, labor minimums, applicable taxes, and overhead and profit within the appraisal estimate.
The documented appraisal result
The appraisal/umpire estimate totaled $19,262.58, which was $17,706.89 above the starting carrier RCV. That is approximately a 1,138.2% increase, or about 12.38 times the starting estimate.
Carrier correspondence in the project file later confirmed that the appraisal had concluded and referenced release of $6,658.81 in recoverable depreciation. That payment figure is not the same as the RCV comparison above; deductibles, depreciation, prior payments, policy terms, and coverage decisions affect actual claim payments.
Why the difference mattered
This project demonstrates why a construction scope should be checked line by line. Measurements, physical conditions, repair sequencing, labor requirements, and supporting documentation can materially change the cost required to complete documented repairs correctly.
Roofing Giant’s role
Roofing Giant documented construction conditions, scope, quantities, pricing, and repair requirements. Roofing Giant did not determine policy coverage or the claim settlement. The appraisal record addresses the amount of loss; the insurer applies coverage and policy terms.
Source note: Figures are drawn from Roofing Giant’s historical project file, including the carrier estimate, appraisal/umpire estimate, and carrier correspondence. The percentage compares documented replacement-cost values, not the homeowner’s net insurance payment.
Original itemized reports
Original source documents — redacted for privacy. Estimate line items and amounts unchanged. All pages available in the retained files are included. Carrier names and branding, item descriptions, quantities, unit prices, taxes, depreciation, overhead/profit and totals have been preserved. Homeowner identifiers, policy/claim numbers and signatures have been removed from the public copies. Unredacted originals remain in Roofing Giant’s private project records.
North Richland Hills — Allstate
Starting Allstate estimate
Open PDF · 6 pagesAppraisal / umpire estimate
Open PDF · 10 pagesThe later document is the appraisal/umpire estimate, not a carrier-written supplement approval. It includes roofing and interior scope. Starting RCV: $1,555.69; appraisal/umpire RCV: $19,262.58.
The PDFs open in a new tab. Replacement cost value (RCV) is not the homeowner’s net payment. Appraisal outcomes and carrier-approved supplements are identified separately.
Source records and calculation
- Starting Allstate estimate on file, dated 23 August 2022: RCV summary, page 5.
- Umpire estimate dated 12 April 2023: RCV summary, page 6; scope recap, pages 8-9.
- Carrier correspondence dated 1 June 2023 confirms the appraisal conclusion and the separate depreciation release.
Increase = ($19,262.58 − $1,555.69) ÷ $1,555.69 × 100. The starting amount is the verified pre-supplement or pre-appraisal carrier estimate available in this project file; it is not represented as the first version the insurer ever created. Values are compared on the same claim and coverage basis.
Unredacted originals remain in Roofing Giant’s private project records; privacy-redacted source PDFs are linked above. Public illustrations exclude customer identifiers. Photos illustrate recorded conditions; they do not prove the cause of damage or coverage.
Make sure the repair scope matches the roof.
Request an inspection and a documented construction-scope review.
Schedule a Free Roof InspectionImportant: These are selected historical outcomes, not a typical-results claim or a guarantee of approval, payment or percentage increase. RCV is not net payment; deductibles, depreciation, prior payments, coverage and policy terms affect what is payable. Roofing Giant is a roofing contractor that manages qualified roofing crews/subcontractors to Roofing Giant standards. Roofing Giant is not a public adjuster and does not determine policy coverage or claim settlement. Appraisal participants determine the amount of loss within the appraisal process; the insurer applies coverage and policy terms. Information only; not insurance, public-adjusting, financial or legal advice.